The Complete KL Property for Sale Guide: What Buyers and Tenants Need to Know
The Complete KL Property for Sale Guide: What Buyers and Tenants Need to Know
If you are looking for a clear, honest walkthrough of buying or renting property in Kuala Lumpur, this KL property for sale guide is written for you. It covers how the market behaves, what to inspect before you commit, the legal and financing steps, and the practical details that separate a smooth t
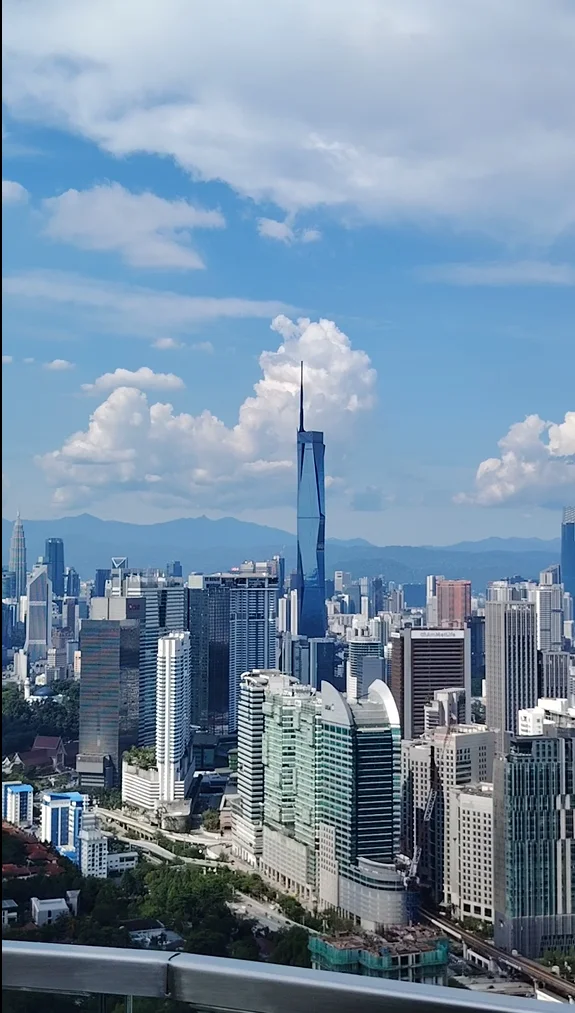
If you are looking for a clear, honest walkthrough of buying or renting property in Kuala Lumpur, this KL property for sale guide is written for you. It covers how the market behaves, what to inspect before you commit, the legal and financing steps, and the practical details that separate a smooth transaction from a costly one — whether you are buying a condo in Bangsar, a terrace house in Cheras, or a serviced residence in the city centre.
1. Understanding the Kuala Lumpur property market
Kuala Lumpur is a mature, segmented market. Prices and demand behave very differently in the city centre (KLCC, Bukit Bintang, Ampang), the established suburbs (Bangsar, Mont Kiara, Damansara Heights), and the mid-to-outer rings (Cheras, Kepong, Setapak, Wangsa Maju). Before viewing anything, you should understand which segment fits your goal: own-stay, rental yield, capital appreciation, or a balance of all three.
Key neighbourhoods at a glance
- Bangsar: Mature, low-density, strong expat and professional demand. Limited new supply, so resale values are stable. Good for own-stay and long-let tenants.
- Mont Kiara: High-rise dense, expat-focused, competitive rental market. Yields can be decent but capital appreciation is slower due to oversupply in some towers.
- KLCC vicinity: Premium pricing, strong for short-stay and corporate lets, but service charges are higher and parking can be limited.
- Cheras & Setapak: More affordable entry points, family-oriented, improving connectivity via MRT Sungai Buloh–Kajang (SBK) and Putrajaya lines.
- Kepong & Sentul: Regeneration areas where older stock sits alongside newer launches — useful for buyers comparing resale versus new.
For transport and accessibility research, the public rail network is a major price factor — properties within a 600–800 metre walk of an MRT or LRT station generally hold value better than those further out. You can verify station locations and lines at rapidkl.com.my before shortlisting areas.
2. How to evaluate a KL property before you commit
Most buyers focus on the unit and forget the building, the neighbourhood, and the title. A proper evaluation should look at four layers: the unit, the building, the location, and the legal status.
What to check at the unit level
- Cracks — especially diagonal cracks above doorframes and around structural walls (not just hairline plaster cracks).
- Water marks on ceilings, near windows, and around bathroom walls shared with neighbouring units.
- Floor unevenness and tile hollowness (tap lightly; hollow tiles will need re-laying).
- Air-cond points and their condensate drainage — a common defect in older condos.
- Direction of facing — west-facing units are hotter and may need heavier air-cond usage; this affects ongoing costs.
What to check at the building level
Ask for the latest audited accounts of the management corporation (MC) or Joint Management Body (JMB). Look at the sinking fund balance, outstanding maintenance arrears, and any special levies. A building with high arrears (typically above 15–20% of total billing) is a red flag — it usually signals future special assessments or declining upkeep. Also check the age of lifts, the condition of the water tank and pump system, and whether the building has a current certificate of completion and compliance (CCC) for any recent additions.
What to check at the title level
Confirm whether the property is on individual title, strata title, or still under master title with a developer. Strata properties without issued strata titles can still be transacted, but the process is slower and depends on developer consent. For commercial-titled serviced apartments, be aware that utility rates, assessment rates, and loan margins can differ from residential-titled units even if the unit is used as a home.
3. The legal process of buying property in Kuala Lumpur
Once you agree on a price, the standard flow in Malaysia is: Offer to Purchase (OTP) or Letter of Offer → booking fee → Sale and Purchase Agreement (SPA) drafting → SPA signing within a set period → payment of balance purchase price (usually 90% for completed property, less booking fee and deposit) → vacant possession and handover. For sub-sale properties, the SPA is normally prepared by the seller's conveyancer and reviewed by your own lawyer; you should always engage your own solicitor, not the seller's, to avoid conflict of interest.
Typical timeline for a completed sub-sale
| Stage | Indicative timeframe |
|---|---|
| OTP / booking | Day 1 |
| SPA signed | Within 14–21 days from booking |
| Balance payment & handover | 90–120 days from SPA (standard); 120–180 days if with loan |
| Strata / individual transfer registered | 3–9 months after handover, depending on land office backlog |
For valuation reference points and official property market reports, the Valuation and Property Services Department (JPPH) publishes quarterly data — see jpph.gov.my. Use it to sanity-check asking prices against transacted values, not just listing prices.
4. Financing, fees, and hidden costs
Buyers often calculate only the purchase price and the loan, then get surprised by the additional costs. For a KL residential property, expect the following categories of cost on top of the price:
Standard buyer cost checklist
- SPA legal fees: Scaled under the Solicitors' Remuneration Order — first RM500,000 at 1%, next RM500,000 at 0.8%, and so on.
- Loan agreement legal fees: Same scale, on the loan amount.
- Stamp duty on transfer (Memorandum of Transfer): Tiered — first RM100,000 at 1%, next RM400,000 at 2%, next RM500,000 at 3%, remainder at 4% (subject to current exemptions, e.g. first-home buyer schemes where applicable).
- Stamp duty on loan agreement: 0.5% of loan amount.
- MRTA / MLTA: Optional but often required by lenders; either one-off or recurring.
- Valuation fee: If the bank's panel valuer is instructed, scaled on valuation amount.
- Service charge & sinking fund: For strata — confirm the per-square-foot rate and arrears status before signing.
- Renovation & defect rectification: Budget realistically; older units in Bangsar and Damansara Heights often need rewiring, replumbing, or roof works.
As a rough rule of thumb, total transaction costs (excluding renovation) typically fall in the range of 3–5% of purchase price for the legal and stamp duty side, plus the deposit. Always get a written fee estimate from your conveyancer before signing the OTP.
5. Common mistakes KL buyers and tenants make
After years of handling KL transactions, the same issues repeat. Avoiding them is often worth more than negotiating a small discount on price.
Mistakes to avoid
- Falling for listing photos: Wide-angle lenses and lighting can make a 700 sq ft unit look like 1,000. Always verify built-up area on the strata plan, not the marketing brochure.
- Ignoring maintenance arrears: A "cheap" unit in a building with 30% arrears can cost you more in special levies than the discount saved.
- Not checking the lease tenure: Most KL residential land is freehold, but some areas (parts of Cheras, Setapak, and certain commercial-titled parcels) are leasehold with 60 or 99 years remaining. Banks lend less willingly as the lease shortens.
- Overlooking facing and ventilation: A unit facing a future high-rise can lose its view, light, and privacy within two years.
- Underestimating commute reality: "10 minutes to KLCC" on a Sunday morning is not the same as 8am on a Monday. Test the commute at the hours you will actually travel.
- Skipping the agent verification step: Always confirm the negotiator is registered with the Board of Valuers, Appraisers, Estate Agents and Property Managers (BOVAEP). You can verify any REN at lppeh.gov.my.
6. Working with a licensed agent vs going direct
Some buyers assume dealing directly with the owner or developer saves money. In practice, a licensed negotiator's value is in due diligence, comparable pricing, paperwork accuracy, and managing the chain between buyer, seller, banker, lawyer, and management office. A registered negotiator is also legally accountable — they operate under BOVAEP rules and must not misrepresent material facts about the property.
I am Shermaine Foong (REN 76742), operating under Shermaine Property. My focus is on KL resale and rental, with particular experience in Bangsar, Mont Kiara, and the city centre. If you want a shortlist tailored to your budget, commute, and intention (own-stay versus investment), you can register interest via shermaineproperty.com and I will reach out with current matched options rather than a generic feed.
Frequently asked questions
Is now a good time to buy property in Kuala Lumpur?
KL remains a buyer-favourable market for completed resale stock, with negotiated pricing common in many segments. The right time depends more on your financing readiness and holding period than on market timing alone — if you plan to hold for at least 5–8 years and have stable income, current conditions are workable.
What is the difference between residential and commercial-titled serviced apartments?
Serviced apartments are usually built on commercial-titled land, which means utility tariffs, assessment rates, and sometimes loan margins differ from residential-titled homes. The unit may feel like a condo, but ongoing costs and certain financing terms follow commercial rules — always confirm the title before committing.
How much deposit do I need to pay?
The standard booking fee is around 2–3% of the purchase price, paid to the estate agency's client account. The full earnest deposit is typically 10% of the purchase price, with the balance 90% due at completion. Booking fees are usually held in a stakeholder account and released per the SPA terms.
Can a foreigner buy property in Kuala Lumpur?
Yes, subject to a minimum purchase threshold set by each state. In Kuala Lumpur, the standard minimum for foreign buyers is RM1,000,000 for most residential strata and landed properties, though certain categories and project types may differ. Foreign buyers also need state authority consent, which adds time to the transaction.
How long does the whole buying process take in KL?
For a completed sub-sale with a straightforward loan, expect roughly 3–4 months from booking to handover. Leasehold properties requiring state consent, or strata units with title issues, can take 6 months or longer. Your conveyancer should flag expected delays at the SPA stage.
Should I use the seller's lawyer to save on fees?
It is not recommended. The same firm cannot act for both buyer and seller without a clear conflict waiver, and even then your interests are better protected by an independent solicitor. The small saving is rarely worth the risk on what is usually your largest single asset purchase.
This KL property for sale guide is intended as a practical reference, not a substitute for specific legal or financial advice. For current listings, viewings, or a tailored shortlist in Bangsar, Mont Kiara, KLCC, or surrounding areas, contact Shermaine directly through shermaineproperty.com — every transaction is handled personally under REN 76742, with full BOVAEP compliance.